


CARBON CREDITS & CARBON MARKETS
Carbon Offset and Insetting Strategy
Choose climate actions with clearer boundaries. Keep every claim evidence-led and reviewable.
AIGreen Plus helps Malaysian manufacturers map residual-emissions questions, distinguish value-chain insetting from external offsetting, and build a documented decision pathway. The proposed work covers evidence readiness, options screening, ownership and review gates. It does not buy credits, certify outcomes or decide legal claims.
Human review retainedCurrent-source check is conditionalFictional dashboard concept
See the review dashboard ↓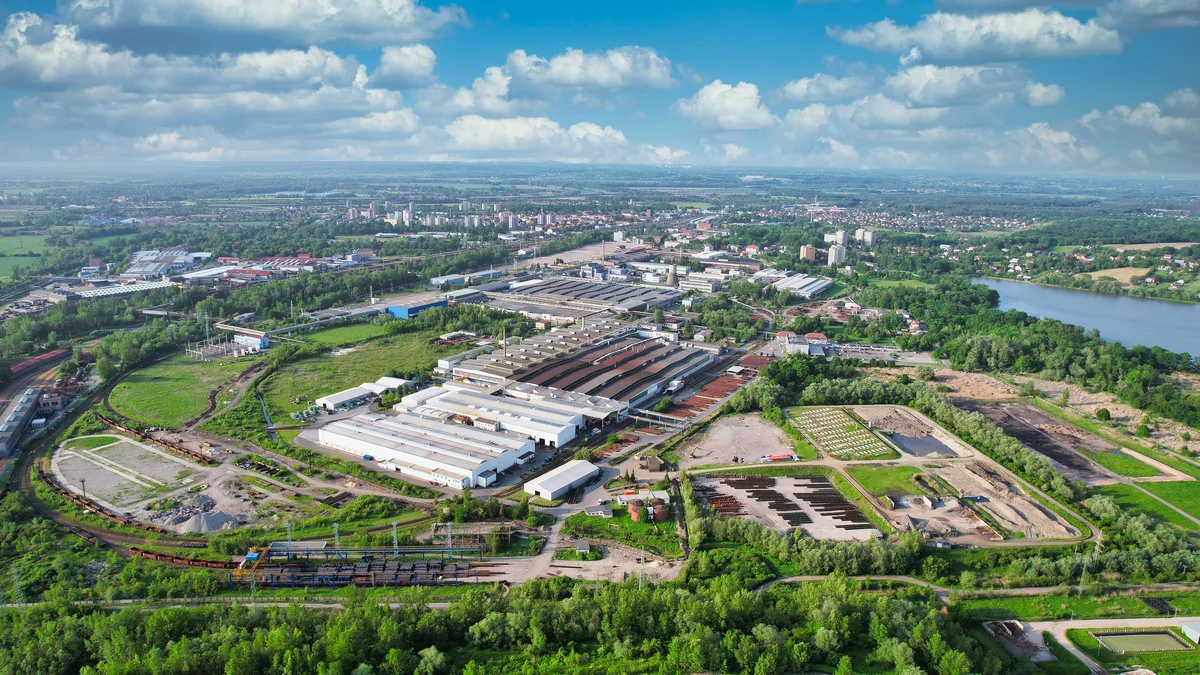
Photo by Daniel Gross · Source: source page · Licence: Pexels License · Resized proportionally and converted to WebP; original content retained. Displayed in a landscape frame.
This consultancy turns a manufacturer’s approved emissions information, value-chain relationships and climate priorities into a bounded offset and insetting strategy. It can compare interventions connected to suppliers or production with external credit options, record assumptions, flag double-counting and evidence gaps, and prepare a review pack. Client owners and qualified advisers retain approval of boundaries, claims, procurement and reporting treatment.
01 / SEE THE REVIEW OUTPUT
Illustrative Climate Action Evidence Review
FICTIONAL SAMPLE / four candidate intervention records. This screen is a static illustration for discussion, not a connected customer system.
PROPOSED DASHBOARD CONCEPT
FICTIONAL SAMPLE / four candidate intervention recordsIllustrative Climate Action Evidence Review
Illustrative candidate records by pathway
Fictional sample values · Fictional classification of the four rows; bars compare candidate pathways, not carbon reductions or quality ratings
Unit: records
| Candidate record | Connection | Evidence items | Review status |
|---|---|---|---|
| Supplier soil-practice pilot | Value chain | 2 | Review logged |
| Packaging recovery programme | Value chain | 3 | Review logged |
| External removal credit option | Outside value chain | 1 | Ready for decision |
| Renewable-energy credit option | Outside value chain | 2 | Review logged |
AI-assisted draft / requires verification
The fictional rows show two supplier-linked options and two external options. Three records have a review logged, while one is marked ready for decision; no emissions reduction, credit quality or claim approval is inferred.
02 / FIVE REVIEW STAGES
Five steps, with an accountable owner.
Evidence, assumptions and open questions move through a human review route. No certification or automatic conclusion is implied.
- 01↓
Scope and boundaries
Define claim and decision boundariesAgree organisational, value-chain, time-period and intended-use boundaries before screening options.
OWNER / CONTROLClient sponsor / consultant - 02✓
Evidence and baseline
Assemble approved activity evidenceCollect approved inventory, supplier, project and prior-claim records while tagging assumptions and gaps.
OWNER / CONTROLData owners / sustainability lead - 03≡
Option screening
Compare insetting and offset routesScreen candidate interventions for relevance, additionality questions, permanence, ownership, leakage and double-counting risks.
OWNER / CONTROLConsultant / qualified reviewer - 04◎
Qualified review
Test claims and decision controlsRun a documented challenge session and route accounting, procurement, legal or tax questions to the appropriate adviser.
OWNER / CONTROLAuthorised client approver - 05↗
Roadmap and handover
Record decisions and next checksDeliver a prioritised roadmap, evidence register, decision log and review calendar without promising outcomes.
OWNER / CONTROLClient owner / consultant
If a check fails: Hold the record for its owner, correct the source and preserve the approved manual fallback.
03 / RESPONSIBILITIES
Organise the work. Keep conclusions with people.
The proposed support can structure records and questions; responsible owners still assess evidence, applicability and decisions.
| Review point | Common starting position | Proposed consultancy support | Responsible reviewer |
|---|---|---|---|
| Set the boundary for residual emissions and climate claims | Boundary notes sit across spreadsheets and meetings | Proposed structured boundary register and review prompts | Authorised owner approves scope and intended use |
| Screen value-chain insetting opportunities | Supplier and project information is compared inconsistently | Proposed evidence matrix for connection, risks and gaps | Qualified reviewer tests relevance and accounting treatment |
| Assess external offset options | Credit documents are gathered and checked ad hoc | Proposed due-diligence checklist and decision log | Client and advisers approve procurement and claims |
| Prepare disclosure support | Narrative and evidence links are reconciled late | Proposed traceable draft pack with open questions | Management signs off wording, figures and limitations |
Separate what is being claimed
Create a boundary and intended-use register that distinguishes inventory, insetting activity, offset purchase and any public statement.
Make decisions traceable
Link each option to approved records, assumptions, owner, review status and unresolved questions.
Prioritise connected action
Compare supplier or production-linked opportunities with external options without assuming feasibility or reductions.
Prepare qualified wording
Draft a review pack that makes limitations, verification needs and adviser questions visible before publication.
04 / HONEST HYPOTHETICAL FIGURES
Show the working behind a planning example.
These figures are modest arithmetic for discussion, not customer evidence, forecasts, emissions claims, payroll promises or guaranteed outcomes.
HYPOTHETICAL WORKED EXAMPLE / NOT CUSTOMER RESULTS
45 → 30 combined labour minutes for the same task.
12 one candidate intervention evidence record units per month × 15 minutes less per unit.
8 → 3 per 100 checked error-affected administrative entries, not incidents/accidents/disease/product defect outcomes (5.0 percentage points).
See assumptions and calculations
| Measure | Illustrative calculation | Meaning and limit |
|---|---|---|
| Labour effort | (45 − 30) ÷ 45 × 100 = 33.3% | Same workload and expected review quality; includes ongoing exception checks as scoped. |
| Time capacity | (45 − 30) × 12 ÷ 60 = 3.0 hours | Released time is not payroll savings or guaranteed job reduction. |
| Admin checks | (8 − 3) ÷ 100 = 5.0 percentage points; 62.5% relative | Separate hypothetical like-for-like review of 100 administrative entries under the same checking definition; figures are illustrative, not measured results or an assurance conclusion. |
Hypothetical same-workload example: a client coordinator spends 45 minutes gathering and reconciling one record, including consultant review and exception follow-up; a structured pack leaves 30 minutes for the same record. It is an administrative-effort illustration, not a headcount, payroll, emissions or procurement saving.
Scenario figures are illustrative arithmetic, not benchmarks, forecasts, actual customer results or guarantees. Measure a like-for-like pilot with the same definitions before making a claim.
05 / PROPOSED DELIVERY
Agree the evidence and review route before work starts.
Confirm scope
Interview owners and document boundaries, intended claims, decision criteria and adviser touchpoints.
What you receiveAgreed scope note and question registerBuild evidence map
Reconcile approved inventory, supplier, project, credit and prior-disclosure records.
What you receiveEvidence register with assumptions and gapsEvaluate pathways
Compare insetting and offset routes against connection, integrity and governance questions.
What you receiveOption matrix and documented review logHandover roadmap
Facilitate approval discussion and capture actions, owners, checks and disclosure limitations.
What you receiveStrategy roadmap and qualified draft support pack06 / BEFORE YOU INVEST
Inputs, boundaries and ownership should be clear.
These lists are a starting point. Final scope, access, professional responsibility and outputs require written agreement.
What to prepare
- Approved organisational and Scope 1–3 inventory information from the sustainability or finance owner
- Supplier, site, commodity and value-chain relationship records from procurement and operations
- Candidate project or credit documentation from procurement or the nominated project owner
- Existing climate targets, public wording and prior claims from the sustainability and communications owners
- Risk, legal, tax and reporting questions supplied by management and its qualified advisers
What to agree in writing
- This is scoped consultancy and decision support; no software is assumed installed and no credit purchase is executed.
- AIGreen Plus does not provide certified assurance, independent verification, legal or tax determinations, or regulator approval.
- Client owners approve boundaries, methods, suppliers, claims, budgets and publication; unresolved questions remain open.
- Use least-necessary approved business data; anonymise supplier or project details where practical and agree access and retention in writing.
- Fees, recurring support, adviser costs, licences, verification and implementation work require a separate written scope; no outcome is guaranteed.
Confidence comes from traceable evidence.
Set definitions, boundaries, source ownership and review responsibility before interpreting a result. A qualified responsible person decides whether a finding is applicable.
07 / CLEAR ANSWERS
10 questions. Practical answers.
Clear answers
Frequently asked questions.
Ten practical answers about scope, sources, review and responsible use.
What does a carbon offset and insetting strategy produce?
It produces a boundary note, evidence register, option comparison, review log and prioritised roadmap. It distinguishes interventions connected to a value chain from external offset options. It does not issue credits, approve a claim, or promise a reduction.
What information should a Malaysian manufacturer prepare first?
Start with the approved emissions inventory or available activity data, supplier and site relationships, candidate project documents, existing targets and public wording. Procurement, operations, finance and sustainability owners should identify what is approved, estimated or missing.
Which method or standard will you use?
The accounting route is agreed during scoping. The GHG Protocol Corporate Standard supports corporate inventory work, while its Land Sector and Removals Standard addresses land emissions and removals. Insetting definitions and treatment remain context-dependent, so qualified review is required.
Who signs off the strategy and any public claim?
The client’s authorised management owner signs off boundaries, procurement and wording. Sustainability, finance, procurement, legal or tax advisers may need to review different questions. AIGreen Plus can prepare evidence and drafts but does not replace those approval roles.
Is this certification or independent assurance?
No. The work can improve readiness and traceability, but it is not certified assurance or an independent verification opinion. Any verification, programme review or assurance engagement must be separately appointed with an appropriately qualified provider.
Are the dashboard and time figures actual results?
No. Dashboard rows and scenario values are fictional planning examples designed to show coherent calculations. They are not customer measurements, emissions factors, credit prices, labour savings, headcount reductions or evidence that an intervention works.
How are confidentiality and access handled?
Access is limited to agreed business records and named roles, with anonymisation where practical. Retention, transfer and access controls are set in writing. This is not a blanket compliance promise; the client should obtain qualified Malaysian privacy, legal or security advice where needed.
Can this work with our existing spreadsheets or systems?
Yes, discovery can use exports, controlled spreadsheets or existing document stores. No integration or installed product is assumed. Feasibility depends on data ownership, permissions, format, history and reconciliation effort, with a manual fallback agreed for gaps.
How long will the work take?
Timing depends on data readiness, stakeholder availability, number of candidate options, review depth and adviser input. The scope can be staged around evidence and decision milestones. A delivery schedule is proposed after discovery rather than promised in advance.
What affects the quote and ongoing support?
Scope, sites, value-chain breadth, number of options, data condition, workshops, adviser coordination, verification needs and reporting outputs affect fees. Recurring monitoring or support is optional and separately agreed; 24/7 support, credit procurement and legal advice are not included by default.
START WITH ONE CLEAR QUESTION
Discuss this outline ↗Discuss Carbon Offset and Insetting Strategy
Share a high-level question and the type of evidence involved—not confidential records. We can discuss discovery, scope and a written way to review the work.
08 / SOURCE NOTES
Check the current public material.
These references support an initial discussion only. They do not make AIGreen Plus an accredited or certified verifier.
Public official material — not accreditation.
- GHG Protocol Corporate Standard
Corporate-level GHG inventory requirements and guidance, including the distinction between inventory accounting and project reductions used as offsets.
- GHG Protocol Land Sector and Removals Standard
The standard’s scope for quantifying, reporting and tracking land emissions and CO2 removals, and its stated effective date of 1 January 2027.
- International Platform for Insetting: What is insetting?
The bounded distinction between value-chain-connected insetting interventions and external carbon offsetting, plus the note that insetting does not always require tradable credits.
These sources support the service’s inventory, removals and insetting/offset distinctions only. Applicability, accounting treatment, claims, verification and legal or tax consequences must be confirmed for the organisation, intervention and reporting period with qualified advisers.
Dashboards and numerical scenarios are fictional planning examples. The services are proposed consultancy scopes, not certification, accreditation, assurance, legal advice, regulatory approval or a promise of emissions, cost, staffing, safety, quality or market outcomes.
