


CARBON CREDITS & CARBON MARKETS
Carbon Neutrality Assessment
Turn fragmented emissions evidence into a reviewable neutrality pathway.
AIGreen Plus can scope a practical carbon-neutrality assessment for Malaysian manufacturers, assemble approved activity evidence, map relevant Scope 1, 2 and selected Scope 3 sources, and document assumptions. Consultants keep calculation choices, claims and next steps subject to client review and qualified external advice.
Human review retainedCurrent-source check is conditionalFictional dashboard concept
See the review dashboard ↓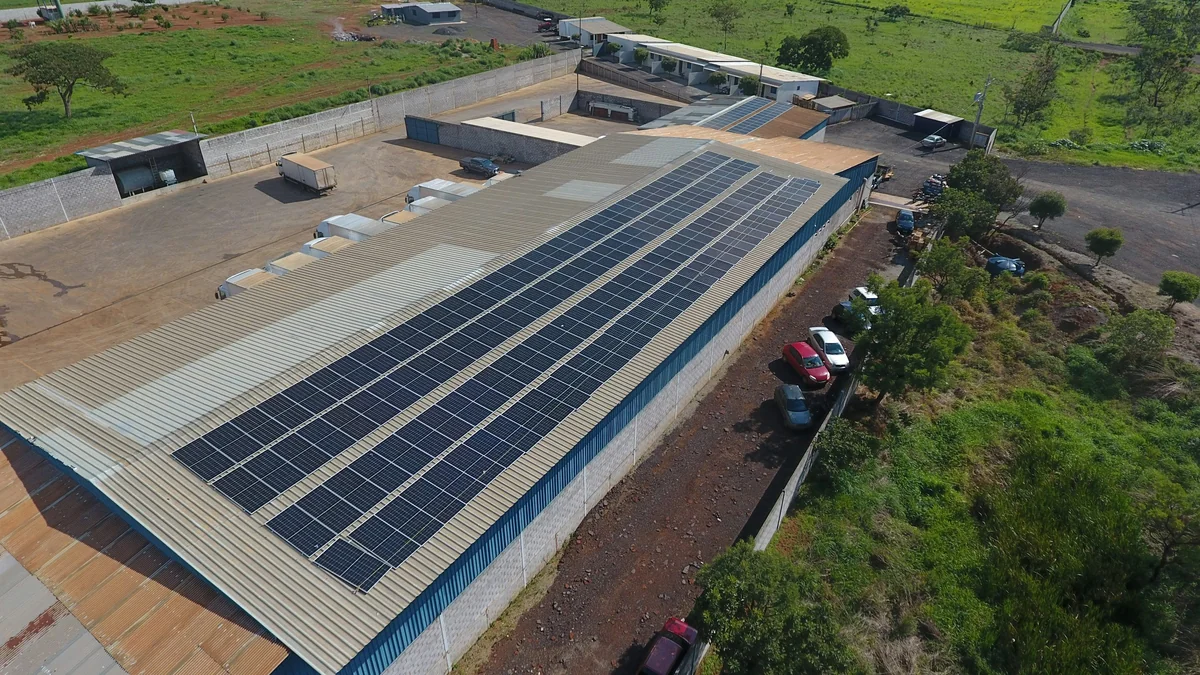
Photo by Rafael Moreno (@rafamrn) · Source: source page · Licence: Unsplash License · Resized proportionally and converted to WebP; original content retained. Displayed in a landscape frame.
This service assesses whether a manufacturer has a sufficiently defined carbon boundary, usable activity data and a defensible pathway for carbon-neutrality planning. We review fuel, electricity, refrigerant, logistics and other agreed sources, distinguish measured records from estimates, and produce an evidence register, gap log and prioritised action roadmap. The output is a consultancy assessment, not a certification, assurance opinion, legal or tax determination, or promise of neutrality.
01 / SEE THE REVIEW OUTPUT
Illustrative neutrality evidence review
FICTIONAL SAMPLE / one assessment workstream, four evidence areas. This screen is a static illustration for discussion, not a connected customer system.
PROPOSED DASHBOARD CONCEPT
FICTIONAL SAMPLE / one assessment workstream, four evidence areasIllustrative neutrality evidence review
Checked records by evidence area
Fictional sample values · Bars compare fictional administrative review counts, not emissions, savings or environmental performance.
Unit: records checked
| Evidence area | Expected records | Checked records | Open gaps | Illustrative basis |
|---|---|---|---|---|
| Scope 1 fuel and refrigerants | 12 | 10 | 2 | Invoices, meter or service records |
| Scope 2 purchased electricity | 8 | 7 | 1 | Utility bills and energy contracts |
| Selected Scope 3 logistics | 10 | 6 | 4 | Freight activity and supplier evidence |
| Neutrality claim support | 6 | 4 | 2 | Reduction, removal or instrument files |
AI-assisted draft / requires verification
Fictional draft: 27 of 36 expected records were checked, leaving nine administrative evidence gaps. The sample suggests follow-up is needed in selected Scope 3 and neutrality-claim files; it does not estimate emissions or approve a claim.
02 / FIVE REVIEW STAGES
Five steps, with an accountable owner.
Evidence, assumptions and open questions move through a human review route. No certification or automatic conclusion is implied.
- 01↓
Define boundary
Agree entity, sites and periodConfirm organisational, operational and assessment boundaries, intended audience and exclusions before calculations begin.
OWNER / CONTROLConsultant / authorised client sponsor - 02✓
Collect evidence
Request controlled source recordsGather approved fuel, electricity, refrigerant, logistics and claim-support records with owners and periods.
OWNER / CONTROLClient data owners / consultant - 03≡
Analyse footprint
Separate facts from assumptionsMap sources to agreed GHG accounting methods, document units and factors, and flag data-quality limitations.
OWNER / CONTROLConsultant / technical reviewer - 04◎
Review pathway
Test reduction-first optionsAssess reduction priorities and any proposed removal or credit evidence without treating them as approved offsets or results.
OWNER / CONTROLClient steering group / qualified advisers - 05↗
Handover controls
Leave a reviewable evidence packDeliver the register, gap log, assumptions, roadmap and claim wording for authorised sign-off and any external assurance decision.
OWNER / CONTROLConsultant / authorised approver
If a check fails: Hold the record for its owner, correct the source and preserve the approved manual fallback.
03 / RESPONSIBILITIES
Organise the work. Keep conclusions with people.
The proposed support can structure records and questions; responsible owners still assess evidence, applicability and decisions.
| Review point | Common starting position | Proposed consultancy support | Responsible reviewer |
|---|---|---|---|
| Set emissions boundary | Teams reconcile site lists and exclusions across spreadsheets. | Proposed structured templates and digital assistance organise boundary evidence. | Authorised management confirms entities, sites, period and exclusions. |
| Reconcile activity records | Staff compare bills, invoices and logs line by line. | Proposed checks flag missing periods, units and duplicates for review. | Data owners validate source records and resolve exceptions. |
| Prioritise reduction actions | Workshop notes and evidence are consolidated manually. | Proposed evidence matrix groups gaps and candidate actions. | Qualified reviewers judge feasibility, materiality and sequencing. |
| Prepare neutrality support | Claim files and assumptions are assembled in folders. | Proposed checklist links claim language to supporting records. | The client and advisers approve any disclosure; no certification is implied. |
Create one evidence trail
Use a source register that links each activity, period, owner and assumption to the assessment boundary.
Make scope choices explicit
Separate Scope 1, Scope 2 and agreed Scope 3 categories so omissions and exclusions can be discussed.
Sequence reduction before claims
Review reduction actions and proposed neutrality instruments with transparent evidence and limitations.
Prepare for informed review
Provide a gap log and handover pack that an authorised team can take to qualified advisers or an external verifier.
04 / HONEST HYPOTHETICAL FIGURES
Show the working behind a planning example.
These figures are modest arithmetic for discussion, not customer evidence, forecasts, emissions claims, payroll promises or guaranteed outcomes.
HYPOTHETICAL WORKED EXAMPLE / NOT CUSTOMER RESULTS
120 → 80 combined labour minutes for the same task.
12 one monthly evidence pack reconciled for a site or source category units per month × 40 minutes less per unit.
12 → 5 per 100 checked error-affected administrative records, not environmental compliance, incidents or emissions outcomes (7.0 percentage points).
See assumptions and calculations
| Measure | Illustrative calculation | Meaning and limit |
|---|---|---|
| Labour effort | (120 − 80) ÷ 120 × 100 = 33.3% | Same workload and expected review quality; includes ongoing exception checks as scoped. |
| Time capacity | (120 − 80) × 12 ÷ 60 = 8.0 hours | Released time is not payroll savings or guaranteed job reduction. |
| Admin checks | (12 − 5) ÷ 100 = 7.0 percentage points; 58.3% relative | Separate hypothetical like-for-like check of records needing correction; values are illustrative, not benchmarks or a service guarantee. |
FICTIONAL same-workload scenario: a client coordinator and consultant spend 120 combined minutes gathering, checking and resolving exceptions before a structured register; the proposed process takes 80 combined minutes including client review and exception effort. It represents administrative effort only, not headcount, payroll, emissions or energy savings.
Scenario figures are illustrative arithmetic, not benchmarks, forecasts, actual customer results or guarantees. Measure a like-for-like pilot with the same definitions before making a claim.
05 / PROPOSED DELIVERY
Agree the evidence and review route before work starts.
Scoping workshop
Agree sites, gases, period, intended claim or disclosure, material exclusions and decision rights.
What you receiveSigned scope note and boundary question setEvidence review
Review approved source files, identify missing activity data and document units, factors and ownership.
What you receiveEvidence register and data-quality gap logNeutrality pathway
Map reduction-first priorities and review any proposed removal or credit evidence without endorsing it.
What you receiveAssumption-led pathway and action roadmapHandover session
Walk authorised stakeholders through calculations, limitations, open items and possible external review routes.
What you receiveAssessment pack, draft disclosures and sign-off checklist06 / BEFORE YOU INVEST
Inputs, boundaries and ownership should be clear.
These lists are a starting point. Final scope, access, professional responsibility and outputs require written agreement.
What to prepare
- Approved site and legal-entity list from the operations or company-secretary owner
- Fuel, refrigerant and process activity records from facilities and maintenance owners
- Electricity bills, meter data and energy-contract attributes from utilities or finance owners
- Selected logistics, purchased-goods or supplier activity evidence from procurement and logistics owners
- Proposed reduction, removal, credit or disclosure documents from the sustainability lead
What to agree in writing
- This is a scoped assessment and roadmap, not certification, independent assurance, legal advice or tax advice.
- Applicability of a method, disclosure or claim is confirmed for the organisation and reporting period with qualified advisers.
- Client-authorised access, retention, confidentiality, anonymisation and approved sharing routes must be agreed in writing.
- Activity factors, estimates and exclusions are assumptions to be documented and reviewed; no carbon or energy reduction is promised.
- External verification, purchased instruments, implementation, recurring monitoring, software integration and ongoing support require separate written scope.
Confidence comes from traceable evidence.
Set definitions, boundaries, source ownership and review responsibility before interpreting a result. A qualified responsible person decides whether a finding is applicable.
07 / CLEAR ANSWERS
10 questions. Practical answers.
Clear answers
Frequently asked questions.
Ten practical answers about scope, sources, review and responsible use.
What does a Carbon Neutrality Assessment produce for a Malaysian manufacturer?
It produces an agreed boundary, evidence register, data-quality and assumptions log, source-level review, reduction-first pathway and handover pack. It does not issue a certificate, assurance opinion or declaration that the manufacturer is carbon neutral.
What information should we prepare first?
Start with the entity and site list, reporting period, fuel and electricity records, refrigerant or process data, selected logistics activity and any proposed credit or removal files. Each source should have an owner, unit, period and approval status.
Which method or standard will you use?
The assessment can be mapped to the GHG Protocol Corporate Standard and its Scope 2 Guidance, with carbon-neutrality concepts considered against the current ISO 14068 family where appropriate. The applicable method and factors are agreed during scoping; paid standards are not reproduced.
Who signs off the boundary and final assessment?
The client’s authorised sponsor confirms entities, sites, exclusions and intended use. Finance, facilities, procurement and sustainability owners validate their records. A qualified adviser should review regulatory or claim implications; AIGreen Plus does not replace that approval.
Does administrative time released mean fewer employees or payroll savings?
No. Any time illustration concerns a defined evidence-reconciliation task and includes review and exception effort. It is not a headcount, payroll, productivity, energy or emissions claim. The client can measure actual effort using agreed time logs after the work, if desired.
Are the dashboard counts and scenario numbers our actual results?
No. They are fictional sample values designed to show how evidence coverage and administrative effort could be discussed. They are not your actual emissions, savings, benchmark, forecast or certification result.
How are confidentiality and access handled?
Use only approved, minimum-necessary records and agreed access channels. Define anonymisation, retention, reviewers and deletion or return terms in writing. A Malaysian privacy or legal adviser should confirm obligations for your data; the service is not a compliance promise.
Can this work with our existing spreadsheets, meters or ERP?
Yes, the initial assessment can work from exported, read-only or manually supplied records if they are authorised and interpretable. Any interface, connector, software licence or installed system is separate and requires discovery, testing, security review and written agreement.
How long will the assessment take?
Timing depends on site count, reporting period, source quality, stakeholder availability and review cycles. We confirm milestones after discovery rather than inventing a duration. Late or incomplete records can move the evidence-review and sign-off dates.
What affects the quotation and what support continues afterward?
Scope drivers include sites, gases, Scope 3 categories, data condition, workshops, language, review depth and any external-adviser coordination. Prices, recurring costs and ongoing support are quoted separately; 24/7 support, monitoring and assurance are not included unless written into scope.
START WITH ONE CLEAR QUESTION
Discuss this outline ↗Discuss Carbon Neutrality Assessment
Share a high-level question and the type of evidence involved—not confidential records. We can discuss discovery, scope and a written way to review the work.
08 / SOURCE NOTES
Check the current public material.
These references support an initial discussion only. They do not make AIGreen Plus an accredited or certified verifier.
Public official material — not accreditation.
- GHG Protocol Corporate Accounting and Reporting Standard
Corporate-level GHG inventory purpose, standardized accounting/reporting, Scope 2 context, and distinction between inventory accounting and verification.
- GHG Protocol Scope 2 Guidance
Purchased or acquired electricity, steam, heat and cooling as Scope 2, plus transparency around energy contracts and instruments.
- ISO 14068-1:2023 Carbon Neutrality page
ISO's public description of carbon-neutrality principles focused on quantifying, reducing and offsetting, and the page's status showing the 2023 edition withdrawn and revised by ISO 14068:2026.
These official pages support bounded accounting and carbon-neutrality-method context only. The ISO page records a withdrawn 2023 edition and revised 2026 version; the applicable edition, claims and Malaysian reporting obligations must be confirmed for the organisation and period with qualified advisers.
Dashboards and numerical scenarios are fictional planning examples. The services are proposed consultancy scopes, not certification, accreditation, assurance, legal advice, regulatory approval or a promise of emissions, cost, staffing, safety, quality or market outcomes.
