


ACCOUNTS & FINANCE / WORKFLOW 34
AI Invoice & Three-Way Matching
Match invoices to orders and receipts. Route exceptions for review.
AIGreen Plus can scope an AI-assisted invoice desk for Malaysian manufacturers: read approved invoice fields, align them with purchase orders and goods-received notes, surface mismatches, and prepare a review queue. Finance retains authority to validate tax, coding, duplicate risk, and payment release.
Human review retainedIntegration subject to discoveryFictional dashboard concept
See the dashboard concept ↓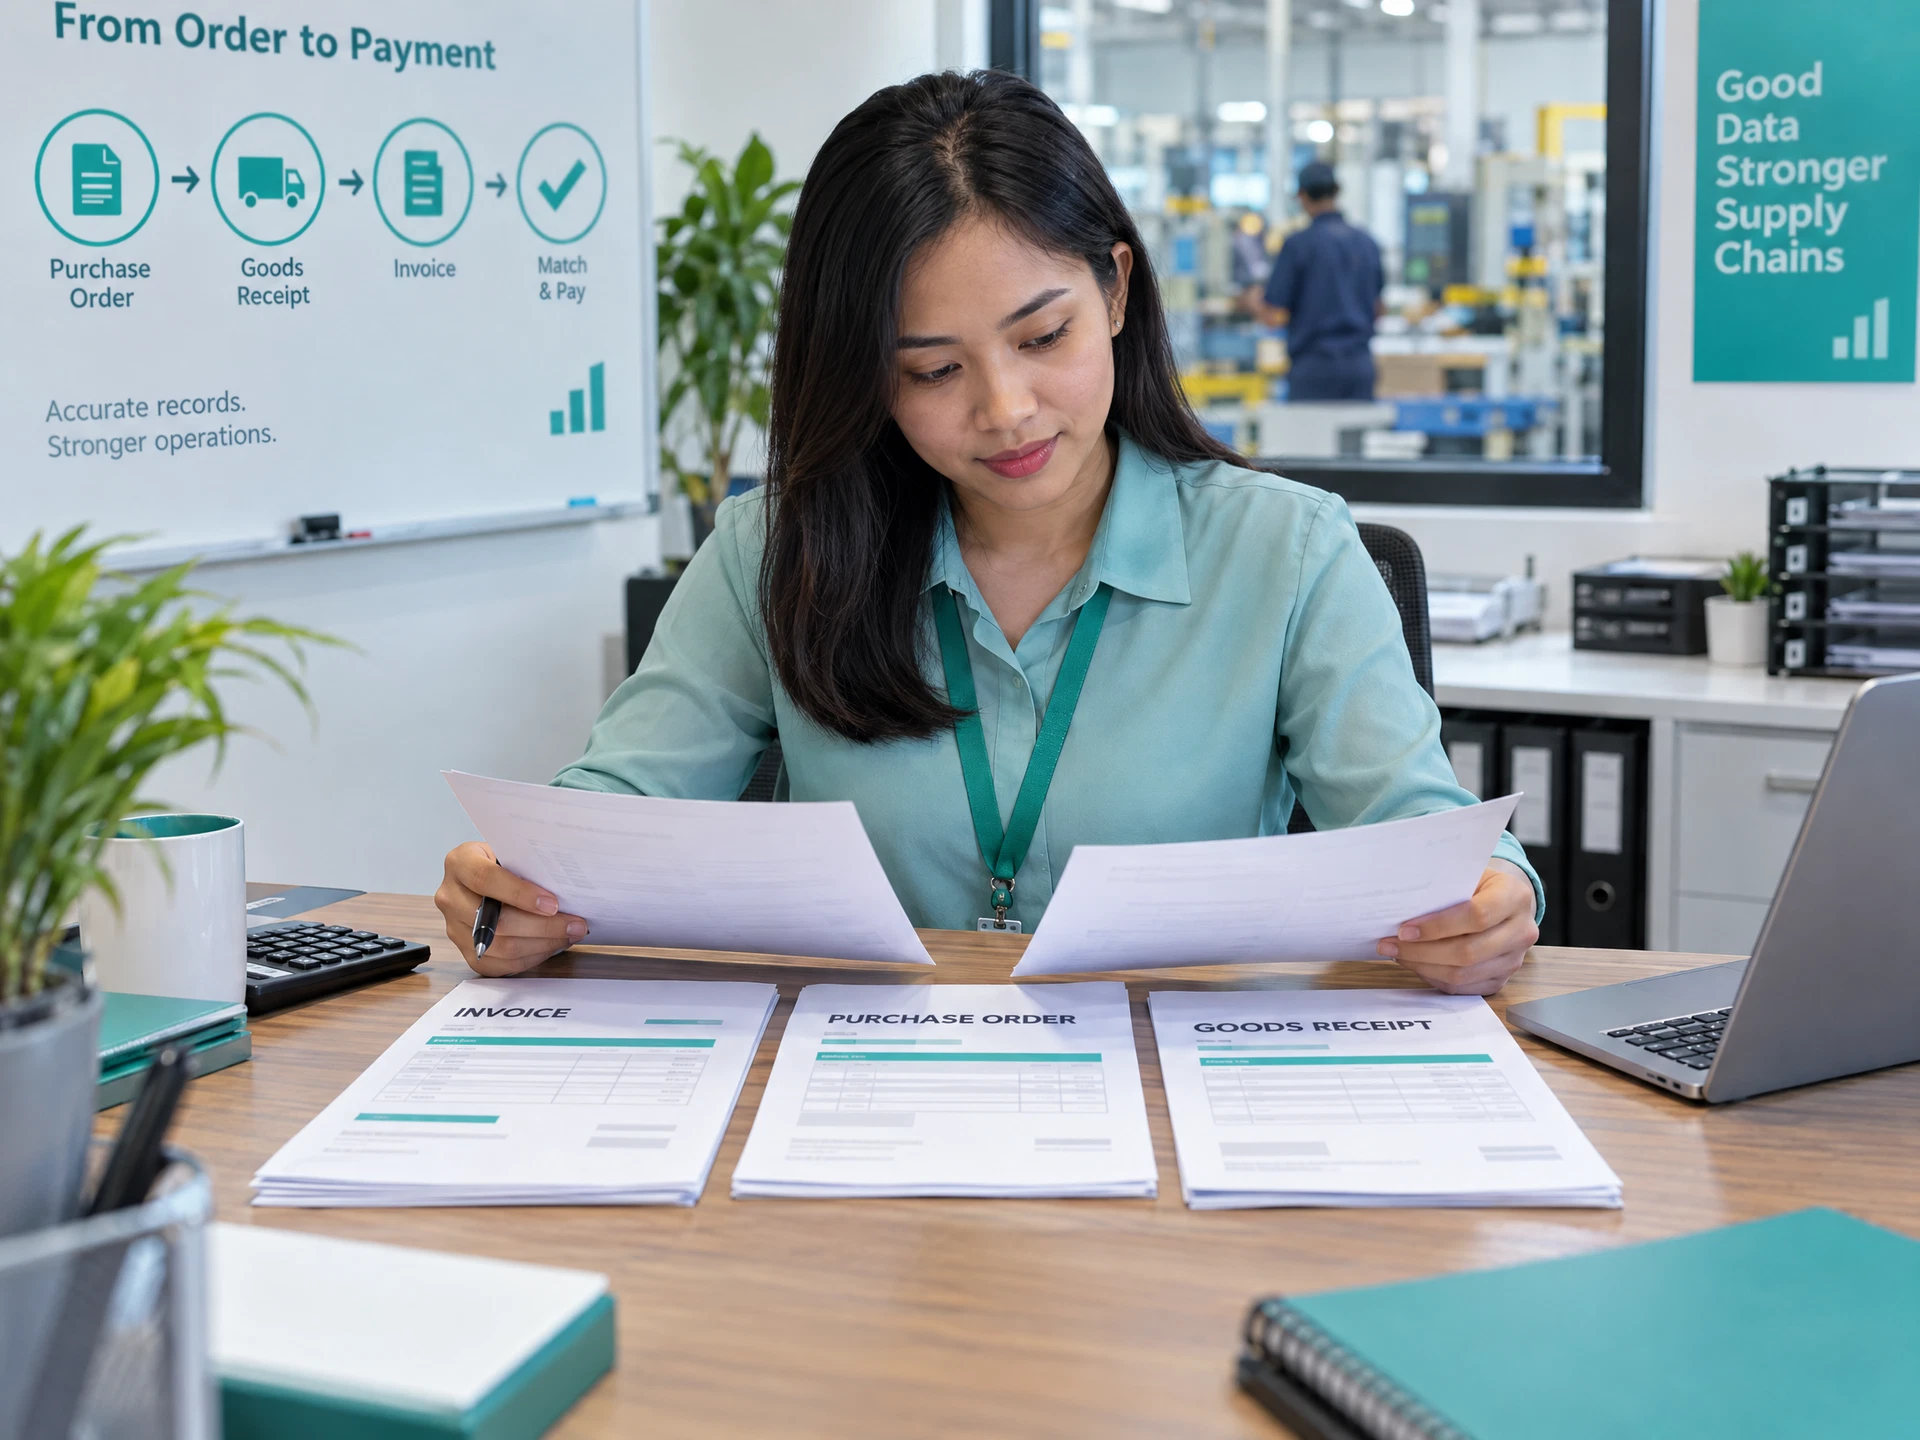
Image status: generating — final scene not yet confirmed.
This workflow helps accounts-payable teams process supplier invoices against the purchase order and goods-received record before a finance decision. A scoped design can extract agreed fields, locate the relevant order and receipt, compare supplier, item, quantity, price, currency and terms, then produce a match status, evidence links and exception reason. It does not book, pay, file tax or override controls: an authorised finance reviewer resolves exceptions and approves any downstream action.
01 / SEE THE OUTPUT
Three-Way Match Review Queue
FICTIONAL SAMPLE / illustrative invoice batch for one month; not customer evidence. A clear view of the records, calculations and exceptions your team may need to review.
PROPOSED DASHBOARD CONCEPT
FICTIONAL SAMPLE / illustrative invoice batch for one month; not customer evidenceThree-Way Match Review Queue
Illustrative exception counts by review reason
Fictional sample values · Bars compare fictional review cues in the sample only; they do not indicate customer performance or a confirmed root cause.
Unit: invoices
| Sample batch | Invoices (count) | Matched (count) | Exceptions (count) | Primary review cue |
|---|---|---|---|---|
| Sample batch A | 18 | 14 | 4 | quantity or price |
| Sample batch B | 12 | 9 | 3 | receipt reference |
| Sample batch C | 10 | 8 | 2 | price or terms |
AI-assisted draft / requires verification
Draft only: the illustrative queue contains invoices marked for match or exception review; review cues require source-document checks, and no payment or accounting decision is made.
02 / THE WORKFLOW
Five steps, with an accountable owner.
The example separates deterministic checks from AI-assisted drafts, exceptions and decisions.
- 01↓
Intake and consent
Confirm scope and sourcesCollect approved invoice, PO and receipt fields.
OWNER / CONTROLAP process owner / data steward - 02✓
Extract invoice fields
Read agreed invoice fieldsDraft supplier, number, line, price and tax fields.
OWNER / CONTROLAI-assisted draft / AP reviewer - 03≡
Link PO and receipt
Find the supporting recordsLink records using approved references.
OWNER / CONTROLProcurement and receiving control - 04◎
Compare and explain
Explain variances with evidenceCompare agreed fields and show evidence.
OWNER / CONTROLFinance control owner - 05↗
Approve or route
Resolve exceptions before postingSend uncertain matches to authorised review.
OWNER / CONTROLAuthorised finance approver
If a check fails: Hold the record for its owner, correct the source and preserve the approved manual fallback.
03 / RESPONSIBILITIES
Automate the repetition. Keep the judgment.
| Task | Manual today | Proposed assistance | Human review / owner |
|---|---|---|---|
| Capture invoice fields | Re-key headers and lines. | Draft fields with a source cue. | Check supplier, tax fields and source. |
| Locate supporting records | Search purchasing and receiving records. | Suggest PO and receipt links. | Confirm supplier, items and transaction. |
| Compare invoice to PO and receipt | Read three records and calculate differences. | Show side-by-side values and reason. | Apply approved tolerance, UOM and currency rules. |
| Route an exception | Track unresolved invoices separately. | Queue evidence, owner and next action. | Resolve under policy; no automatic payment. |
Create a traceable invoice draft
Use agreed fields and source references for verification.
Make the three records easier to reconcile
Suggest PO and receipt links; expose uncertainty for confirmation.
Standardise exception explanations
Turn approved variance rules into review prompts, not policy.
Give finance a prioritised review queue
Show evidence, reason, owner and next action for approval.
04 / TRANSPARENT FIGURES
Show the working behind the claim.
These numbers show one hypothetical calculation method. They are not customer evidence.
HYPOTHETICAL WORKED EXAMPLE / NOT CUSTOMER RESULTS
24 → 12 combined labour minutes for the same task.
60 one supplier invoice reviewed against its purchase order and goods-received record units per month × 12 minutes less per unit.
7 → 3 per 100 checked error-affected invoice-check entries requiring correction, not payment losses, tax findings, safety incidents, product defects or customer outcomes (4.0 percentage points).
See assumptions and calculations
| Measure | Illustrative calculation | Meaning and limit |
|---|---|---|
| Labour effort | (24 − 12) ÷ 24 × 100 = 50.0% | Same workload and expected review quality; includes ongoing exception checks as scoped. |
| Time capacity | (24 − 12) × 60 ÷ 60 = 12.0 hours | Released time is not payroll savings or guaranteed job reduction. |
| Admin checks | (7 − 3) ÷ 100 = 4.0 percentage points; 57.1% relative | Hypothetical like-for-like administrative check using the same source documents and reviewer gate; not a control, compliance, accounting or outcome guarantee. |
Hypothetical same-workload, same-quality assumption: one invoice check takes 24 minutes manually versus 12 minutes with draft extraction and matching plus reviewer and exception handling; 60 invoices per month, with identical approval gates.
Scenario figures are illustrative arithmetic, not benchmarks, forecasts, actual customer results or guarantees. Measure a like-for-like pilot with the same definitions before making a claim.
05 / PROPOSED DELIVERY
Scope one process, then measure it.
Map the three-way process
Confirm invoice fields, PO and receipt keys, tolerance rules, exception categories and authorised finance decisions.
What you receiveSigned workflow map and field/control inventoryPrepare a safe sample
Assemble approved, anonymised documents covering ordinary matches, missing links, quantity differences and price differences.
What you receiveRedacted sample pack and test casesDesign the review queue
Prototype extraction, evidence display, exception routing, manual fallback and an audit-friendly review record.
What you receiveReview-screen or report prototype with acceptance checklistTest and hand over
Run agreed scenarios with finance, procurement and receiving owners, record findings and document the approved operating boundary.
What you receiveTest findings, decision log and scoped next-step proposal06 / BEFORE YOU INVEST
Inputs, boundaries and ownership should be clear.
What to prepare
- Approved anonymised supplier invoice PDFs or structured files, owned by the accounts-payable process owner.
- Approved purchase-order headers and line data, owned by the procurement or ERP data owner.
- Approved goods-received records with receipt references and quantities, owned by the warehouse receiving owner.
- Approved supplier, item, currency and unit-of-measure reference data, owned by the finance or procurement data steward.
- Approved tolerance matrix, duplicate-check rules, coding guidance and escalation list, owned by the finance controller.
What to agree in writing
- Finance approval remains mandatory: the workflow may draft a match status and exception reason but cannot post entries, release payment, file tax returns or change supplier master data.
- Only approved, least-necessary invoice, PO and receipt fields enter the pilot; redact bank details and personal contact data where not required, and obtain Malaysian privacy and security review before access.
- Source tolerances, duplicate rules, currency and unit-of-measure handling and escalation paths require written sign-off from authorised finance and procurement owners; ambiguous records go to manual fallback.
- Any ERP, inbox, storage or OCR interface, role access, retention, audit trail, licensing, testing and rollback is scoped and agreed in writing; no integration is implied.
- Pilot effort, recurring service, model or OCR usage, training and support are quoted after volume and exception discovery; ongoing support hours and response times are not assumed.
Confidence comes from traceable evidence.
Define the baseline and acceptance criteria before a pilot, trace outputs to approved sources, record review and exception effort, and make a scale/revise/stop decision with the process owner.
07 / CLEAR ANSWERS
10 questions. Practical answers.
Clear answers
Frequently asked questions.
Ten workflow-specific questions on scope, integration feasibility, controls, costs and measurement.
What does this matching workflow do?
It drafts invoice fields, suggests the related PO and goods-received record, compares agreed values, and queues evidence and exceptions. It never posts, pays, files tax or makes the final finance decision.
Can it use our existing ERP?
Possibly, after discovery of formats, access and fallback. AIGreen Plus claims no specific integration. Start with approved exports or samples; any live interface is separately specified and agreed in writing by authorised owners.
What data is needed first?
Provide redacted invoices, POs and goods-received records, plus supplier and item references, tolerances, duplicate rules and escalation contacts. Share representative matches and exceptions only, excluding unnecessary bank or personal data.
Who approves matches and exceptions?
An authorised finance reviewer decides whether a tolerance applies, a receipt is valid and an invoice may proceed. Procurement or receiving can clarify source records, but an AI draft cannot substitute for approval.
Do released minutes mean payroll savings?
No. The illustration describes administrative effort under assumptions, not payroll savings, job elimination or guaranteed capacity. Measure review time, rework and corrections on agreed samples while preserving approval quality and segregation of duties.
Are the dashboard figures actual results?
No. Dashboard, chart, time and administrative-error figures are fictional examples, not customer evidence, benchmarks or forecasts. A pilot needs an agreed baseline and documented measurement method before comparison with actual records.
How are access and privacy handled?
Use least-necessary fields, redaction, role access and written retention and audit controls. Finance and security owners should review Malaysian data handling, vendors and locations; this is not a compliance or certification promise.
When is the first milestone?
Timing depends on sample readiness, document variation, rule clarity, access and reviewer availability. Agree the first milestone after discovery; it may include a process map, test pack and prototype. No fixed duration is promised.
What drives quotation and recurring cost?
Cost depends on volume, document types, OCR or model usage, exceptions, interfaces, security review, testing, training, storage and support. A proposal should separate one-time work from recurring usage; no price is implied.
Who owns support after handover?
Nominate process and technical owners for rules, access, source quality and exceptions. Agree support hours, change handling, licences and fallback separately; ongoing ownership and 24/7 support are not automatic or included.
START WITH ONE REPEATABLE TASK
Discuss the workflow ↗Discuss Invoice & Three-Way Matching for your operation.
Share the process and the type of information involved—not confidential records. We can discuss discovery, access boundaries and an agreed way to measure a scoped pilot.
New AI-created images are fictional scenes; the production-reporting photograph is licensed Pexels stock. None depicts actual AIGreen Plus staff, clients, facilities, workflows or results.
All dashboard values and benefit scenarios are fictional; the screen is not a live integration. Workflows, system access, privacy, responsibilities, licences, costs and support require written scope. No ranking, savings, staffing, safety, quality or compliance outcomes are guaranteed.
